What Is a Cap Rate? Formula, Examples, and Why the Highest Yield Rarely Wins
Cap rates are one of the most referenced metrics in commercial real estate. The cap rate, otherwise known is "capitalization rate," is used to benchmark pricing, evaluate acquisitions, and compare performance across markets and asset classes. They are simple in concept but complex in practice. For investors, understanding what drives cap rates and how they behave through market cycles is essential to making sound investment decisions. Too often, they are interpreted as a standalone indicator of value. In reality, a cap rate tells part of the story but rarely the whole picture.
At Lightstone DIRECT, cap rates serve as a starting point for analysis rather than the final verdict. They help frame how we assess risk, price opportunity, and position assets within their respective markets. But just as a tenant’s lease rate doesn’t capture their overall value to an asset, a cap rate doesn’t capture everything that matters about a deal. It must be interpreted in context, informed by fundamentals, and supported by disciplined underwriting.
What Is a Cap Rate? The Capitalization Rate, Defined
A cap rate reflects the relationship between a property’s net operating income (NOI) and its market value, or purchase price. It is calculated by dividing the annual NOI by the property’s value. A property generating $1 million in NOI that trades for $20 million has a 5.0% cap rate. In this example, the investor is earning an unlevered yield of 5.0% before financing. Another way to think about it is that a 5.0% cap rate is equivalent to paying a 20x multiple of NOI, similar to a 20x price-to-earnings (P/E) ratio in the stock market.
Cap rates fall across a spectrum. Lower cap rates typically correspond to prime locations, strong tenants, long leases, and greater confidence in income growth. Alternatively, a low cap rate could also be due to lower than market occupancy levels, it’s distressed, or there is substantial upside in rents. Higher cap rates often indicate more uncertainty, whether from weaker locations, shorter lease terms, more volatile cash flow, or lower market liquidity.
They also differ across property types. For example, multifamily is often viewed as more resilient because people need housing through cycles and vacancy is spread across many tenants. The broad tenant base, recurring turnover, and deep buyer pool often translate into lower perceived risk and therefore lower cap rates than most real estate asset classes.
Industrial pricing can hinge heavily on tenant quality, lease duration, and the number of tenants. Assets with long-term, creditworthy tenants or diversified multi-tenant rent rolls generally command tighter cap rates. Conversely, buildings leased to a single tenant, shorter remaining lease terms, or tenants with weaker credit profiles typically trade at higher cap rates to compensate for the added income risk. As an example, a single tenant industrial building leased to Amazon on a 10-year NNN lease will trade at a substantially lower cap rate compared to a similar building leased to non-investment grade tenant, all else being equal.
Cap rates also vary significantly by market. A multi-tenant industrial facility located in a high-growth market like Dallas, Texas, can trade significantly below comparable assets in slower-growth or less liquid market such as St. Louis, MO. The properties could be identical in terms of tenant mix and building specs, but investor expectations around rent growth, liquidity, and long-term resilience are not. Cap rates are ultimately a snapshot of market sentiment at a moment in time, reflecting how investors price income durability and future performance.
Why Investors Use Cap Rates to Compare Real Estate Deals
Cap rates provide a common language for evaluating how income translates into value. They allow investors to compare assets of different size, geography, and business plan by expressing income as a yield. They also serve as a reference point for how the market is pricing risk and growth at a given moment.
Investors and appraisers often use market cap rates to derive value from NOI, interpret relative pricing between markets, and understand the level of perceived risk embedded in an asset. Lower cap rates generally signal stronger tenant credit, better locations, and higher expectations for rent growth, while higher cap rates often reflect greater uncertainty.
However, cap rates alone can mask the deeper dynamics that drive returns. Two properties with identical cap rates can still perform very differently depending on tenant profiles, market fundamentals, capital needs, and supply and demand conditions. A higher going in cap rate does not guarantee superior returns, and a lower cap rate does not automatically imply weaker performance. This point is illustrated in the example below.

Deal B may be located in a stronger market with higher rent growth, better credit, and deeper liquidity at exit. It may have longer lease terms, more predictable operating costs, or a more compelling mark to market story. Deal A, despite its higher initial yield, may face slower growth, weaker tenant retention, capital intensive improvements, or a less liquid exit environment.
The initial yield does not determine the ultimate return. Cap rates are helpful, but they do not capture market strength, tenant durability, future NOI growth, or exit pricing. Understanding the drivers behind the cap rate is essential for evaluating real performance.
Cap Rate Formula: How to Calculate Cap Rate (With Examples)
Cap Rate = Net Operating Income (NOI) ÷ Property Value
Example: $1,000,000 NOI ÷ $20,000,000 value = 5.0% cap rate
Cap rates are highly sensitive to small changes in NOI or value. Because they are expressed as a ratio, even modest adjustments can shift perceived yield significantly. For example, if a property generating $1 million in NOI is valued at $20 million, the cap rate is 5.0%. If the value decreases to $18 million, the cap rate rises to 5.56%. This change may seem minor, but it represents a difference of $2 million in pricing.
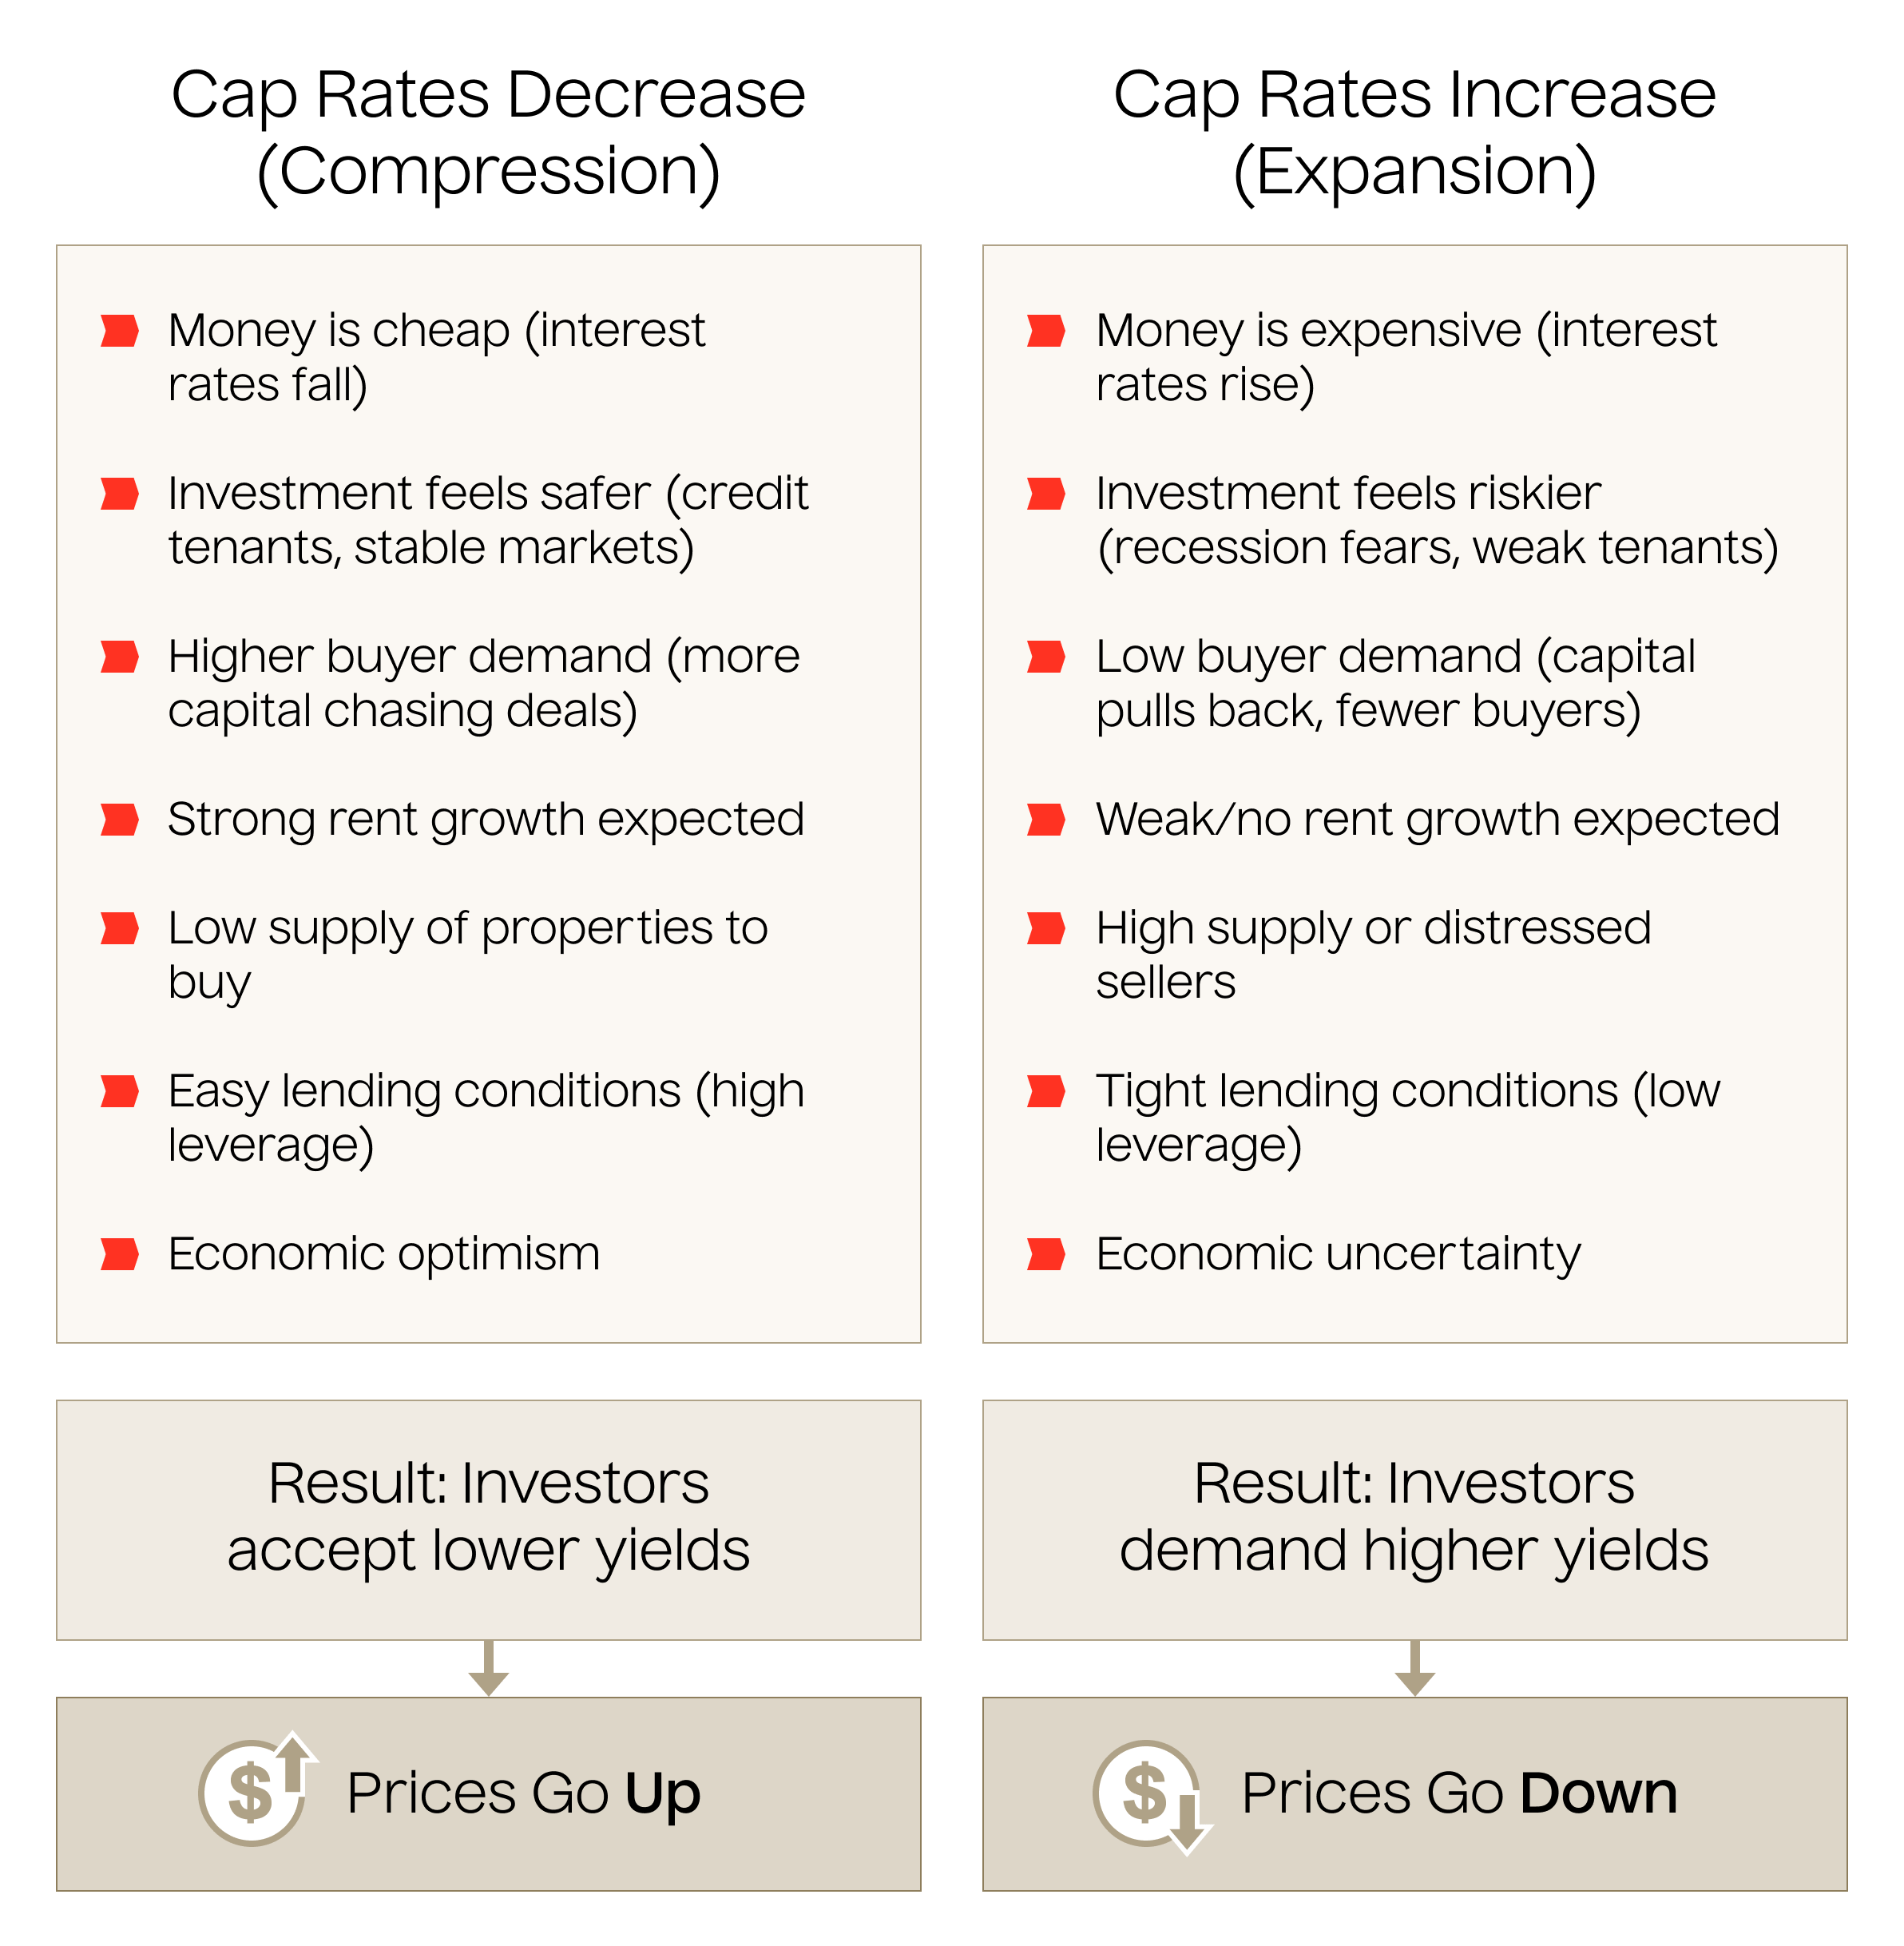
This sensitivity underscores the importance of understanding the underlying assumptions. Cap rates are not fixed; they move with market conditions and investor expectations. Rising operating costs, changing rent rolls, or shifts in tenant credit can all influence NOI and therefore alter an asset’s implied yield. Sophisticated investors analyze these marginal effects to understand how small operational or market shifts might impact total return over time.
What Is a Good Cap Rate?
Nobody asks whether $400 a square foot is a good price without asking what the building is. The same holds for cap rates. A 7% cap rate on a 300-unit garden-style community in a growing Sun Belt suburb and a 7% cap rate on a single-tenant warehouse with three years left on the lease are the same number and nothing like the same investment. One prices a diversified stream of rent checks that keep arriving when a handful of tenants move out. The other prices a single check and a countdown clock.
So the answer to "what is a good cap rate" is a short list of questions, not a percentage.
What asset class? Multifamily has historically traded at lower cap rates than office, retail, or hospitality, because housing demand is steady and the buyer pool is deep. [Insert current national multifamily and industrial cap rate ranges from a named survey — CBRE, Green Street, or NCREIF — with the survey date. Do not publish without the source.]
What market, and what's the growth story? A 4.5% cap rate in a market adding jobs and households is priced for rent growth. A 4.5% cap rate in a market losing both is priced for something else, and the difference will not show up in the cap rate itself.
What does debt cost? A cap rate below the interest rate on the loan is negative leverage: borrowing costs more than the asset yields going in, and the business plan has to close the gap. That is not automatically a bad deal, but it is a deal where the investor is underwriting execution, not income in hand. When the cap rate sits comfortably above the cost of debt, the reverse holds.
What is the cap rate compared to? This is the question that matters most, and the one the headline number hides. The value-add example above starts at a 4.75% going-in cap rate in a 5.0% market. Read alone, that looks like overpaying by a quarter point. Read against the 5.84% stabilized yield on cost the renovation plan produces, it is the setup for an 84-basis-point spread and the entire return.
A high cap rate can flatter a weak asset just as easily as a low one can flag a strong one. The only cap rate that is "good" on its own is the one an investor can explain: why the seller accepted it, what the buyer is underwriting to, and where the comparable trades sit.
At Lightstone DIRECT, we underwrite value-add deals to the spread between stabilized yield on cost and the market cap rate, not to the going-in cap rate. That will not be the right lens for every deal. A stabilized, fully leased asset with no business plan is judged on its cap rate against the cost of debt, and a lower yield on a bulletproof lease can be the better trade. But for the multifamily and industrial value-add deals we bring to investors, the going-in cap rate is a starting point and the spread is the thesis.
Cap Rate vs. Yield on Cost: Where the Spread Comes From
Yield on cost is similar to a cap rate, but it uses total project cost instead of market value. It measures what the investor actually earns after completing improvements or lease up. Cap rates help describe how the market is pricing income today. Yield on cost describes what the investor is creating through execution.
If an investor spends $12 million all in and generates $720,000 in stabilized NOI, their yield on cost is 6.0%. If comparable assets trade at a 5.0% market cap rate, the stabilized value would be $14.4 million. The difference represents value created through execution, assuming cap rates remain consistent. A useful way to see this relationship in practice is to look at a value-add example where NOI growth pushes yield on cost above the market cap rate.
Value Add Example: Using NOI Growth to Push Yield on Cost Above Market Cap Rates
Let’s assume we are purchasing a 100 unit, 95.0% occupied multifamily property at a 4.75% going in cap rate where market cap rates are at 5.0%. Current in place rents are $1,200 and our business plan is to increase rents to $1,550 by implementing $8,000 per unit of capex to improve the property. To make this investment pencil, our yield on cost once our business plan is executed should be above the prevailing market cap rate of 5.0%.
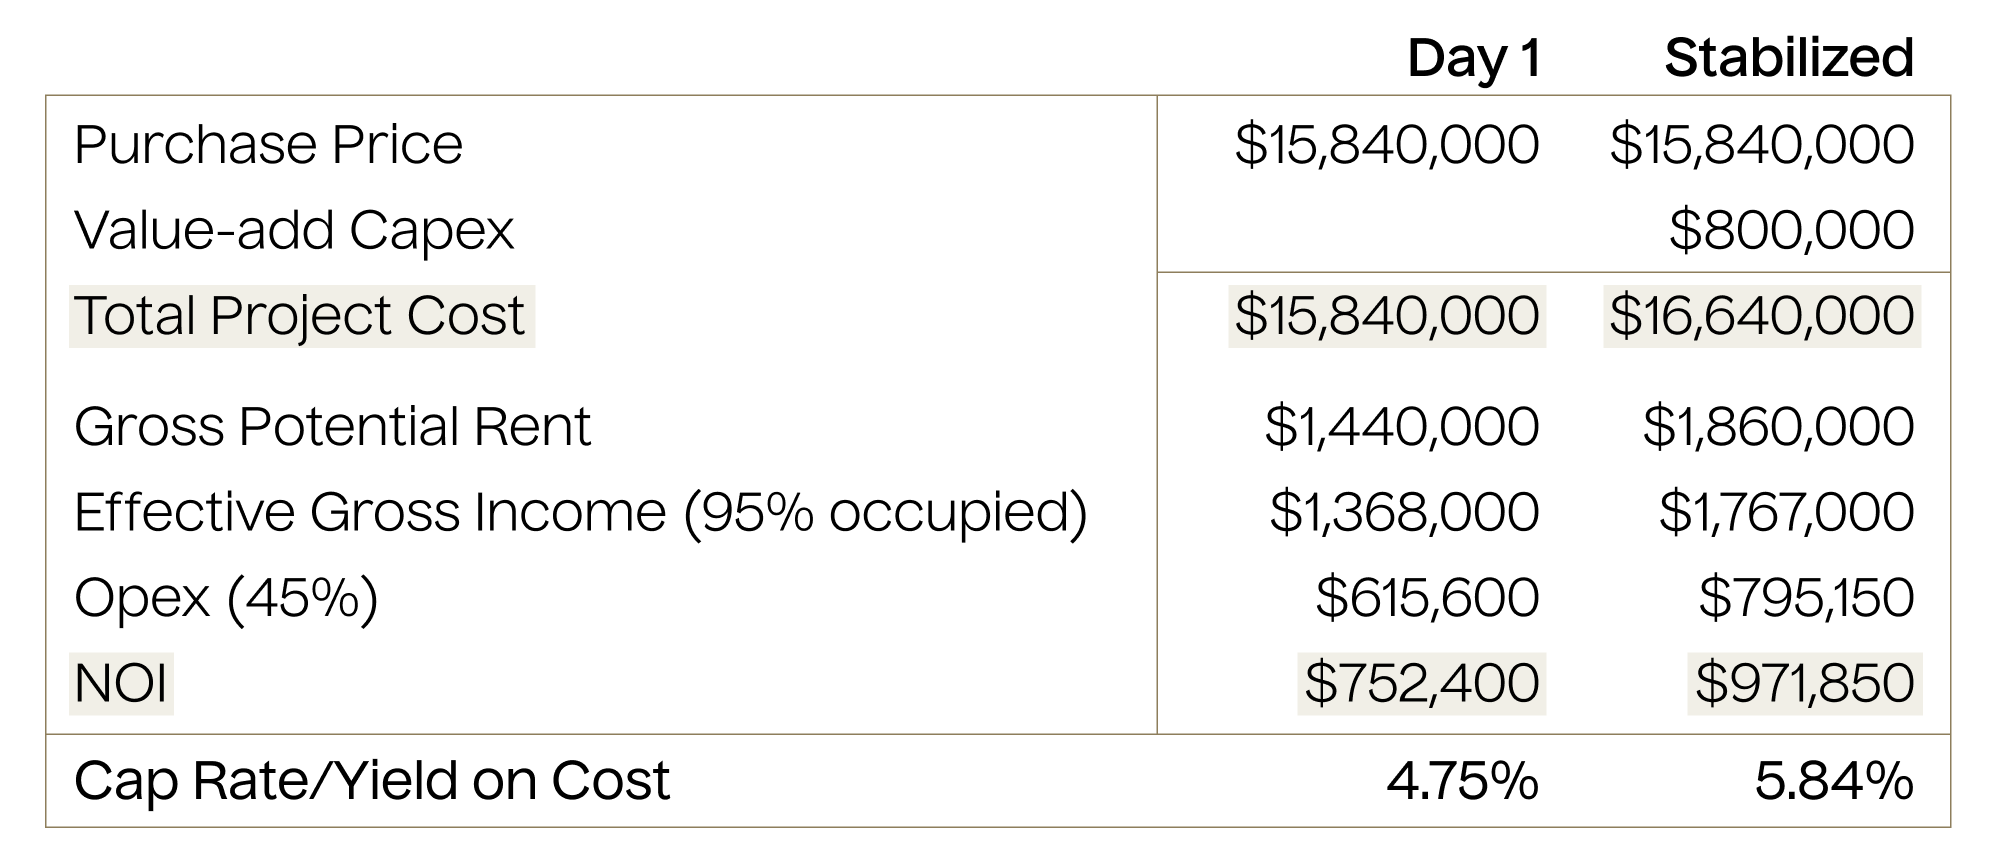
On day one, the investment is purchased at a going in cap rate below the 5.0% market cap rate. Once the business plan is executed and NOI increases, the stabilized yield on cost moves to 5.84%, which is above the market cap rate. That 0.84% spread between what the market is paying for stabilized income and what the investor has created on their total cost is the essence of value add. This translates to a 16.8% gross profit margin (5.84-5.00%/5.00%). If we purchased the property assuming a 50% LTC (purchase + cap ex), this would translate into a 33.6% return on equity (16.8% Gross Profit / 50% LTC).
The Takeaway: Look Beyond the Cap Rate
Cap rates are an important tool, but they are only one piece of the equation. They must be interpreted in the context of interest rates, growth assumptions, tenant credit, and capital structure. Investors who focus solely on the cap rate risk missing the underlying dynamics that truly drive performance.
The best opportunities often balance current yield with quality and growth. A disciplined approach looks past short-term spreads and focuses on total return — income plus appreciation — over the full hold period. This perspective helps protect downside while positioning assets for long-term success.
Cap rates tell you how an asset is valued today. Real value comes from understanding what drives that income tomorrow. For investors, the takeaway is clear: don’t chase the highest cap rate. Focus on the sustainability of cash flow, the quality of tenants, and the fundamentals of the market. Those are the elements that create durable value through all stages of the cycle.
How do interest rates affect cap rates?

Over long periods, cap rates have tended to move in the same direction as interest rates, because buyers compare a property's yield with what they could earn on bonds and what they pay to borrow. The relationship is not one-for-one. Expectations for rent growth, the amount of capital chasing real estate, and property fundamentals can widen or narrow the gap for years at a time.
Does a cap rate include mortgage payments?
No. A cap rate uses net operating income, which is calculated before debt service, so it measures a property's unlevered yield regardless of how it is financed. Two buyers paying the same price for the same building see the same cap rate even if one borrows heavily and the other pays cash. To see the effect of debt, look at cash-on-cash return or levered IRR.
What is the difference between a cap rate and IRR?
A cap rate is a snapshot: one year of net operating income divided by price. IRR, or internal rate of return, is a projection of the annualized return over the entire hold, including income growth, capital spending, financing, and the eventual sale price. Two properties with the same cap rate can produce very different IRRs.
What is the difference between a going-in cap rate and an exit cap rate?
The going-in cap rate is a property's first-year net operating income divided by its purchase price. The exit cap rate, also called the terminal or reversion cap rate, is the rate a sponsor assumes when projecting the sale price at the end of the hold. Because a small change in the exit cap rate moves the projected sale price significantly, it is one of the most important assumptions to check in any deal projection.
What is a cap rate?
A cap rate, short for capitalization rate, is a property's net operating income divided by its market value or purchase price. It expresses a year of income as a percentage of what the property costs, which gives investors a common way to compare pricing across properties of different sizes, markets, and asset types.
What is a good cap rate?
There is no single good cap rate. Whether a cap rate is attractive depends on the asset class, the market's growth outlook, the cost of debt, and what the cap rate is being compared to, such as comparable trades or the stabilized yield on cost a business plan can produce.